
Trending
Nigeria’s cash problem and the 'unintended' consequences of new banking taxes
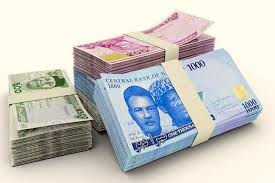
The recent reports of a new 7.5% Value Added Tax (VAT) on card issuance by banks, transfers, and USSD transactions have dominated public discourse, triggering widespread concern and heated debates across Nigeria.
At a time when the country is still grappling with controversial tax reforms, this development has further widened existing tensions and deepened public anxiety. Many Nigerians, particularly those who are not digitally inclined, have expressed fear and confusion over what they perceive as the government’s unclear intentions. The policy, whether well-meaning or not, appears poorly understood by the very people it will affect the most.
This anxiety is not abstract. On the streets, conversations now revolve around a growing “fear of the unknown.” In one such discussion I encountered, several people openly stated their intention to withdraw their money from banks entirely. Their reasoning was simple: uncertainty breeds distrust, and distrust pushes people toward cash.
For a country like Nigeria, such reactions should not be dismissed lightly. Policy design and implementation require a deep understanding of local realities. Nigeria already suffers from a significant trust deficit in financial institutions and digital financial services. Any additional policy that appears punitive or poorly communicated risks worsening an already fragile situation.
The data supports this concern. As of November 2025, figures published by the Central Bank of Nigeria (CBN) showed that out of N5.2 trillion in currency in circulation, N4.9 trillion about 94% was outside the banking system. In October 2025, N4.6 trillion out of N5.057 trillion in circulation, representing 90.9%, was outside the banks. In September 2025, N4.4 trillion out of N4.9 trillion, or 89.7%, was outside the banking system, according to CBN data.
This trend is troubling. Analysts have attributed the growing volume of cash outside the banking system to policy failures, erosion of public trust, and Nigeria’s longstanding preference for a cash-based economy. These factors are deeply intertwined.
Nigeria remains largely an informal economy. Millions of people operate outside formal financial structures, relying heavily on cash for daily transactions. In such an environment, policies that increase the cost of digital banking especially without clear communication and public education may unintentionally discourage financial inclusion rather than promote it.
Market traders across the country already complain of shrinking profit margins. When new policies are introduced in ways that suggest additional financial burdens, many see them not as reforms but as threats to survival. Without careful implementation that reflects Nigeria’s economic realities, even well-intentioned policies risk pushing more people out of the banking system.
Ultimately, policies that deepen fear, mistrust, or confusion may drive the country backwards. For Nigeria to move forward, especially in its push toward financial inclusion and a less cash dependent economy, government actions must inspire confidence not uncertainty.
_thumbnail.jpeg)